
 Posted by
Our 5-year variable mortgage was coming up for renewal in December 2026. I had been eyeing that date for over a year, as it was unlikely my variable mortgage at Prime minus 1.19% (equivalent to 3.26%) would be available at renewal.
At the beginning of each year, I try to guess what will happen in the markets that year. Here’s what I said about the mortgage renewal back in February this year:
I am keeping a close eye on interest rates. Our mortgage is coming up for renewal in December of this year. We’ve been enjoying (and at certain times suffering) with our variable mortgage at Prime minus 1.19% rate for the past 5 years. Today, this is equivalent to 3.26%.
If I were to renew right now, the rates are closer to 3.8-3.9% for either fixed or variable mortgages. It’s not great. I’d expect interest rates to stay relatively flat, fluctuating between a small band of +/- 25bps based on the rate today.
And as with every guess, I end up eating my words later in the year. Here’s what happened with my mortgage renewal.
Reached out to mortgage brokers and bank reps 120 days out
Around August, I reached out to a mortgage broker I’ve previously worked with and to mortgage representatives at the big banks. We have an uninsured mortgage around ~$600,000 outstanding.
The quotes from the reps were largely the same:
- 3-Year Fixed: 3.99%-4.14%
- 5-Year Fixed: 4.24%
- 5-Year Variable: Prime minus 0.8% (equivalent to 3.65%)
I’m still a big believer in variable rate mortgages generally being financially superior to fixed rate mortgages for borrowers. However, I had a few considerations:
- Given there wasn’t much of a gap between Variable and Fixed, I was leaning towards fixed rates.
- There was a 25bps difference between the 3-year and 5-year rates. Given the US federal elections is also just two years away, I am thinking that there may be a shift in the macroeconomic and global trading environment that should be improved versus today. If I went with a three year mortgage, it would give about a year of time for any US policy change to roll through the markets before I had to shop for another renewal. I was leaning towards a three year fixed rate.
In early September, I took these rate quotes back to my existing lender and they were able to offer me 3.94% for a 3 Year Fixed. But they needed me to immediately give up my Variable (P-1.19%) and shift to the 3.94% Fixed. I really didn’t want to do that …
I knew the bond yields were ticking up higher in August but thought I’d have a few more weeks to decide before volatility set in. Boy, was I wrong …
5-Year bond yields jumped 25bps within 2 weeks
Government of Canada – Benchmark 5-Year Bond Yield
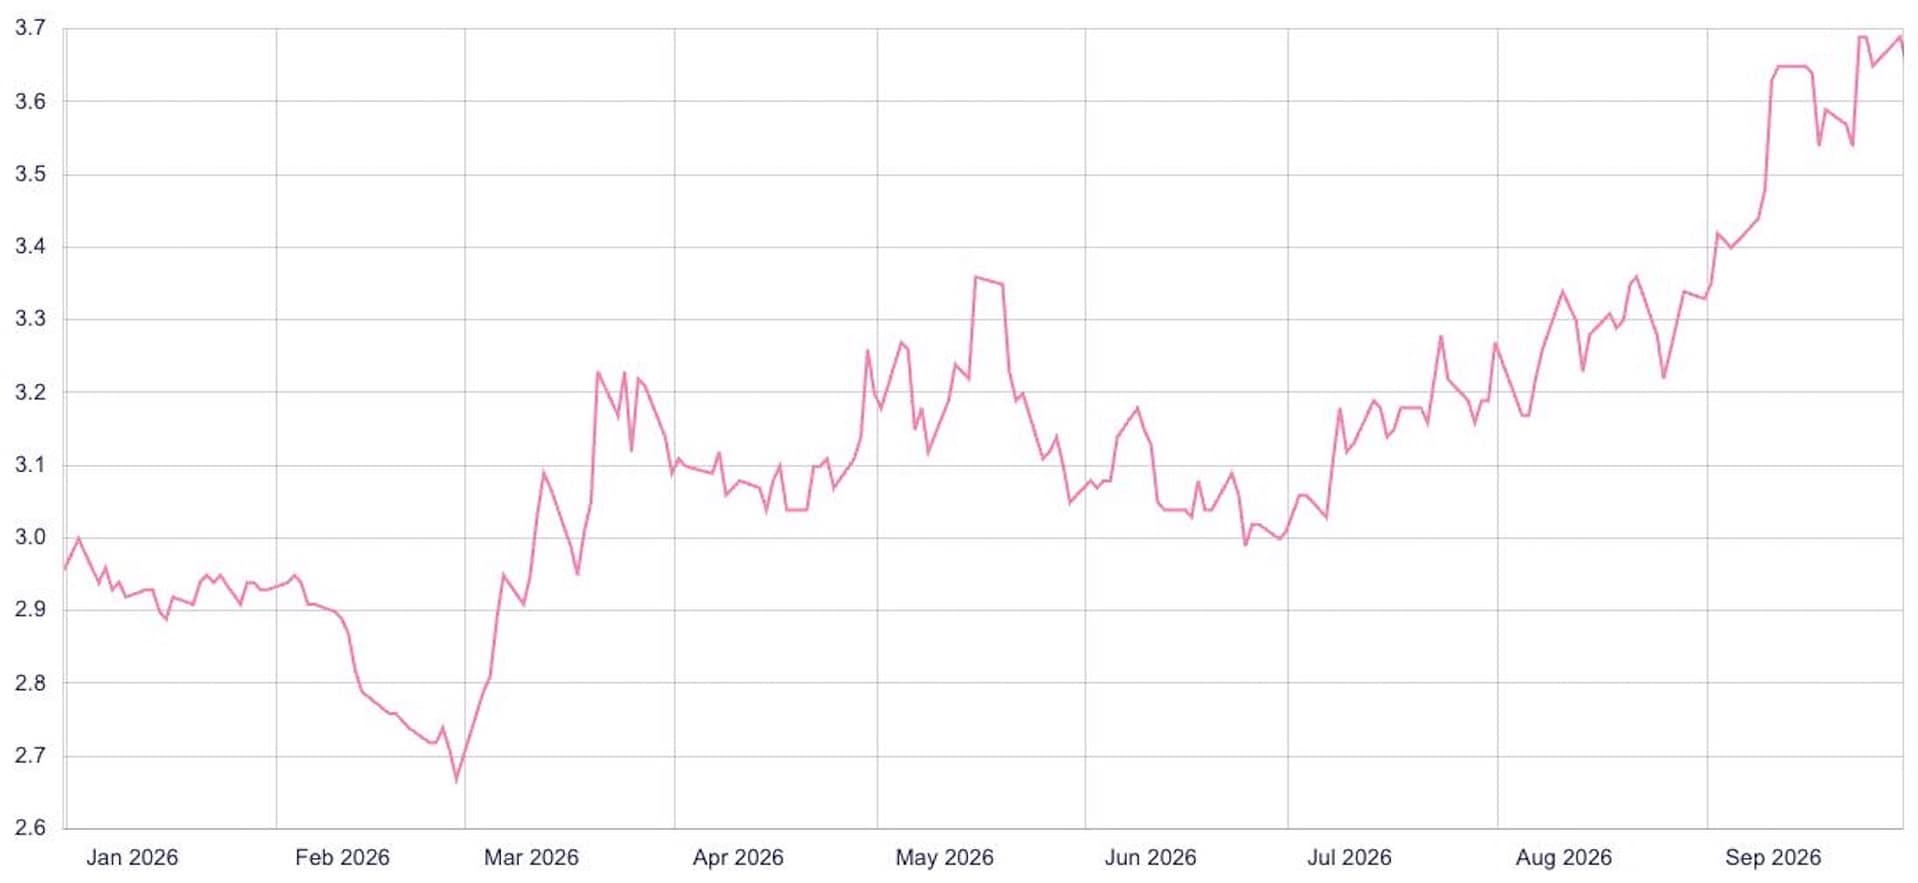
Within a week, my existing lender adjusted up the 3-Year Fixed up to 4.14%, a 20bps difference within a matter of days!
By mid-September, I knew I had to make a choice. At the absolute latest, I could switch lenders around 6 weeks out, which puts it at around mid-October. Is there enough indicators that rates would significantly change over the next 4 weeks? All the headline news were indicating further upward pressure on yields.
I had enough of the lack of certainty. I ended up locking in for a 3-Year Fixed 4.14% mortgage, renewing about two months earlier than my mortgage maturity date.